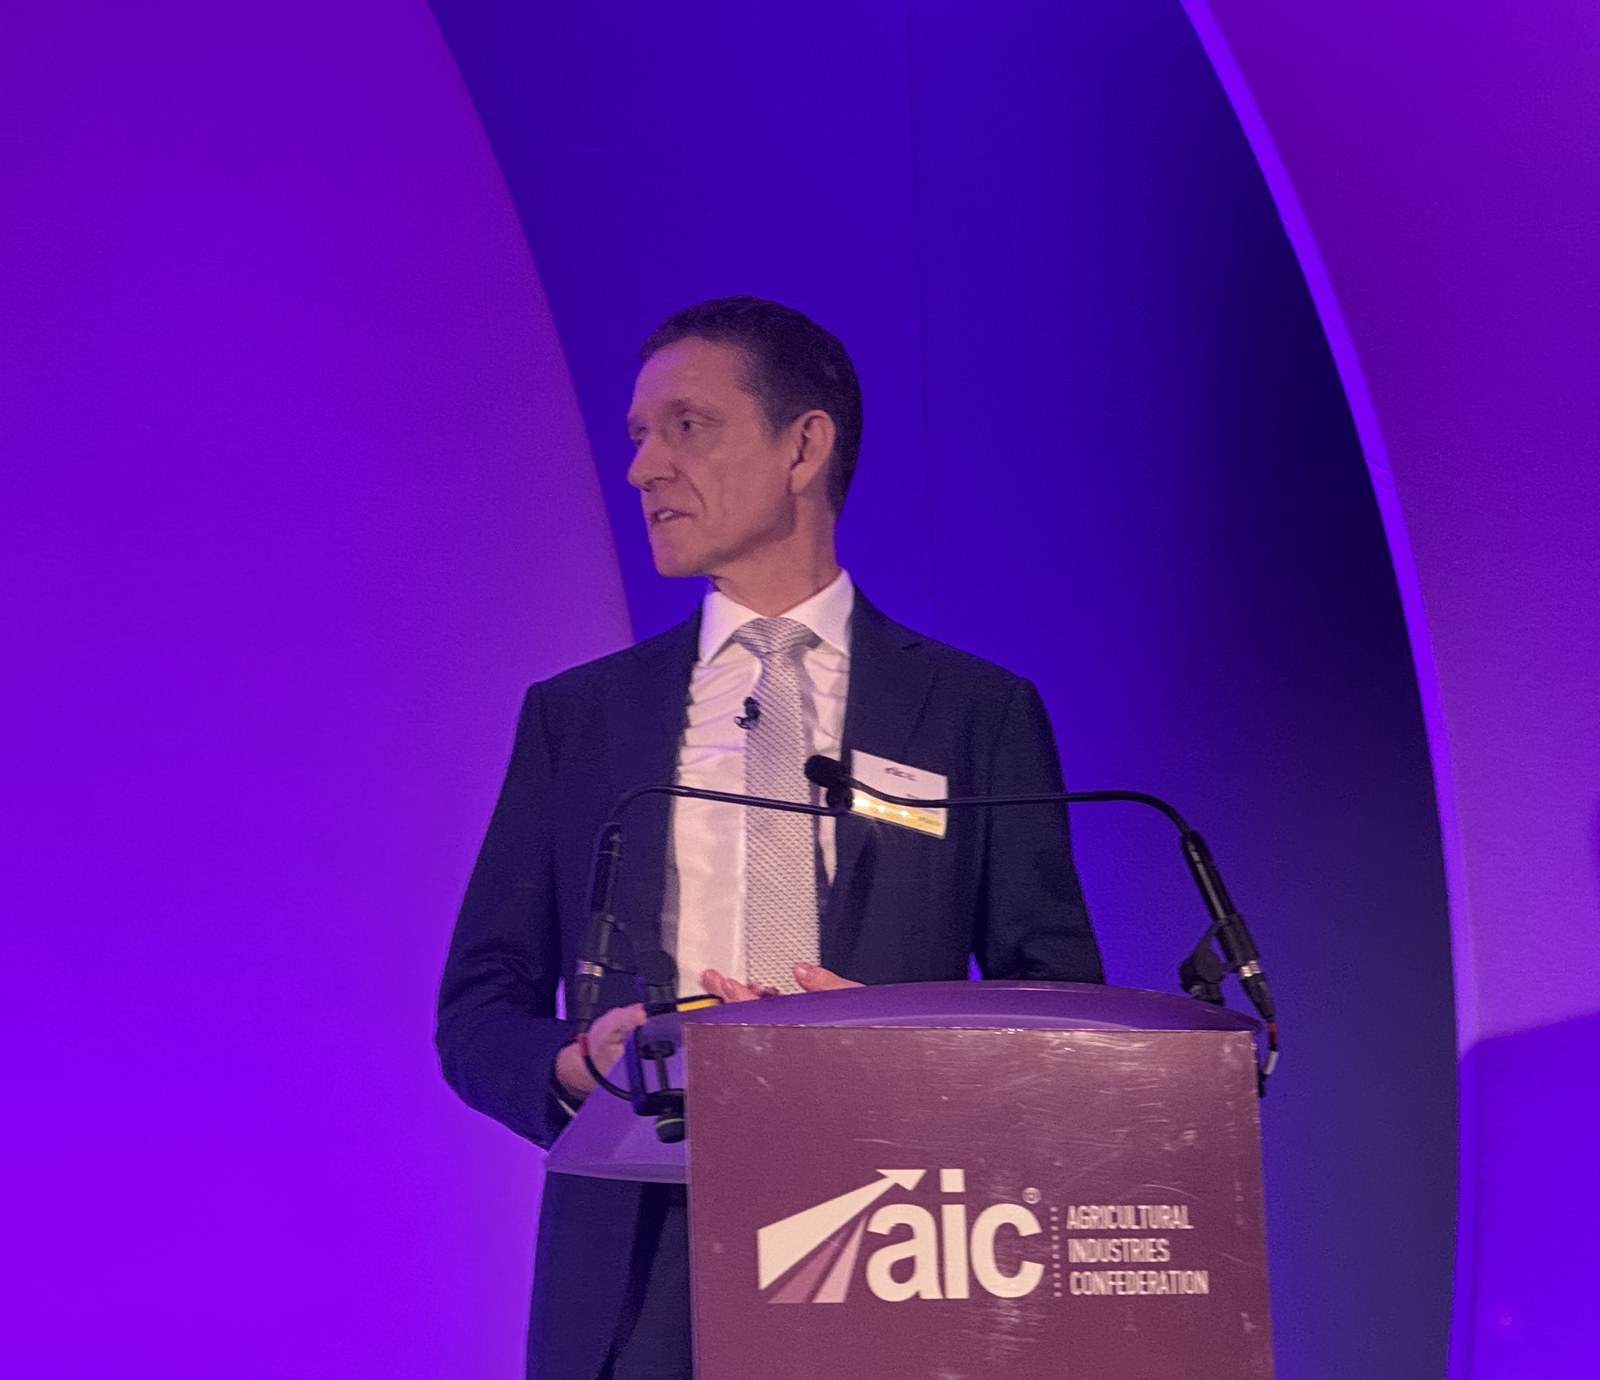
AIC Conference 2026, Peterborough. Arnaud Petit, Executive Director, International Grains Council
The International Grains Council doesn’t grow a tonne of wheat, but its monthly report is what half the trade quotes when they tell you why your price is what it is. So when its executive director, Arnaud Petit, stood up at the AIC conference in Peterborough on Wednesday, it was worth hearing what’s actually driving the market.
Petit, a Frenchman who ran commodities and trade at Copa-Cogeca before taking over the IGC in 2018, had a plain message. There’s plenty of wheat. World production for 2026/27 is forecast at 820m t, down 3% or 25m t on last year. But last year was a record, up 40m t, so this is still the second biggest wheat crop the world has ever grown.
What’s changed is who grew it. The big exporters are down from 437.5m t to 395.5m t, with the EU off 10m t at 133.2m t and the US dropping from 54m t to 41.7m t. The importers had a good year. Turkey went from 18m t to 22.8m t, Morocco doubled to 7.3m t, and Egypt and Algeria are both up. Countries that grew more need to buy less, and the IGC reckons world wheat trade will fall by about 15m t, mostly in North Africa and the Near East. Indonesia imported a record amount last year and is sitting on stocks.
The price chart got a few winces. The IGC’s wheat export price index is 46% below its May 2022 peak, the 14-year high after the Black Sea blew up. It touched a three-year high this summer and is still 12% up on a year ago, but it’s come back since and is only 2% higher than in mid-July when the Black Sea escalated. The market feels there’s enough supply wherever you look, and that’s keeping a lid on it. Petit admitted 2026/27 is “not necessarily a very optimistic” year for trading.
Shipping is where things have changed most. Since 2022 more vessels have been going round the Cape of Good Hope instead of through the Red Sea, adding 15 to 20 days a trip. Same number of ships, longer journeys, so less capacity, and the cost of hiring a vessel has gone through the roof. That’s nothing to do with oil, he said, and he doesn’t see it easing while routes stay disrupted. For importers, freight can add 20% on top of the price of the grain. He called it make or break.
Black Sea shipments are falling. Russia is moving grain out through the Baltic and Ukraine is leaning more on Romania. Argentina, if its harvest comes good, and India, sitting on about 60m t of wheat stocks, could fill the gap later in the season. March 2027 is the point he’s watching.
Then the bit closest to home. Fert prices spiked early this year when Persian Gulf exports were disrupted. The Gulf supplies 30% of the world’s urea exports and half its sulphur. Urea has corrected a bit, partly on Chinese exports, but DAP is still around $950/t on his chart and he doesn’t expect fertiliser to get cheap quickly while gas supply is still disrupted.
He doesn’t think the wheat area will drop for harvest 2027. The risk is how much N goes on. Cutting nitrogen hits quality more than yield, and milling wheat is already the tightest market in the world. If growers trim rates next spring, milling premiums for 2027/28 could be where it shows.
The dollar matters too. It hit an 18-month high in October. Grain is traded in dollars, so a strong dollar leans on prices, and for importers whose own currency has slid, like Egypt, Turkey and Indonesia, wheat hasn’t got any cheaper. Petit said Ghana hasn’t seen the wheat price fall in local money since 2022.
His last point was biofuels. The policy push used to be climate change. Now it’s energy security, having something to fall back on if oil supply goes wrong. World biodiesel output is heading for a record 76.1bn litres this year, up 8%. In the US most of the growth is from used cooking oil and fats, which has roughly tripled, while Indonesia’s is all palm oil. He reckons sustainable aviation fuel could be an opportunity for UK farmers, given the size of our airports.
The flip side is soymeal. The US and Brazil crushing for biodiesel has left a lot of meal looking for a home, and some importers are already swapping feed wheat for it. The plants are built, so he doesn’t see that going away.
The IGC puts a summary of its Grain Market Report on its website every month. Most of us only hear it second hand from the merchant, so it’s worth a look before your next marketing conversation.
So, with fert where it is, are you holding back on N for milling wheat next year or going for the premium?
Join the discussion on The Farming Forum.